CBSA Updates Trade Compliance Verification Priorities
An essential analysis of the Canada Border Services Agency semi-annual verification targets, valuation methods, and origin audit rules affecting Canadian commercial importers.
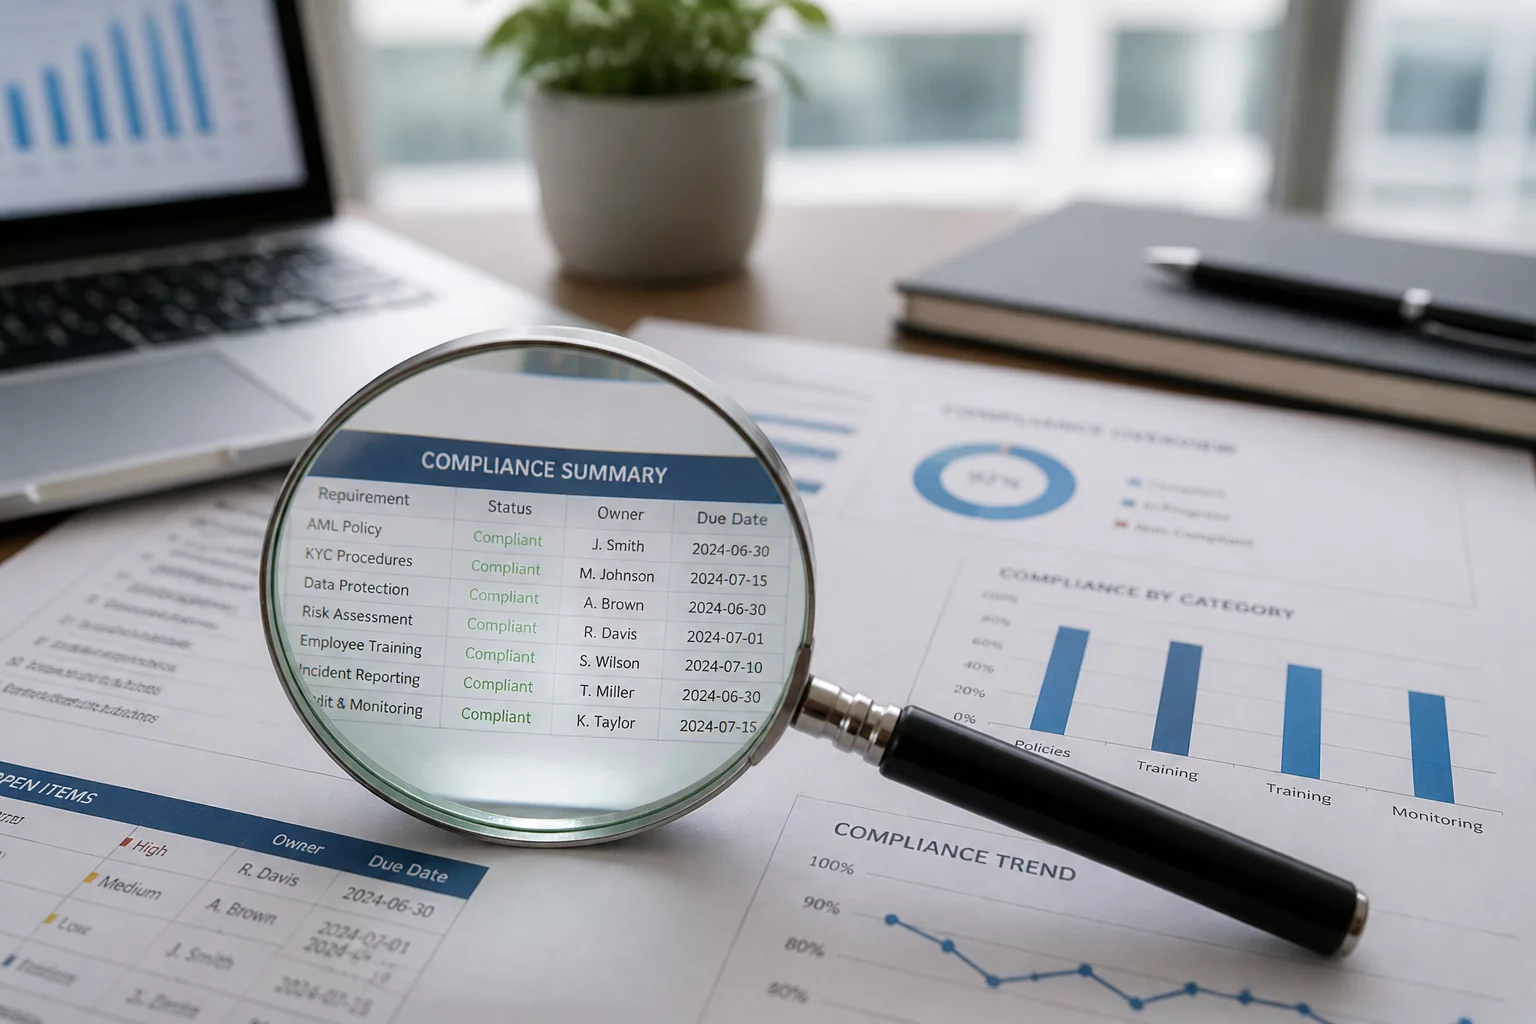
CBSA Heightens Verification on Key Tariff Classifications & Origin Rules
The CBSA published its semi-annual list of compliance verification priorities. Primary focus areas included tariff classification, customs valuation, origin verifications under CUSMA, CETA, and CUKTCA, and supply-managed imports.
Key Assessment Points
-
01
Harmonized Tariff Scrutiny Immediate audit focus on tariff lines including apparel, footwear, optical fibers, and industrial machinery parts.
-
02
Valuation & CARM Integration Cross-matching declared transactional values against transfer pricing adjustments and CARM financial security records.
-
03
Origin Rules & Free Trade Accords Stringent verification trails for preferential duty treatment claimed under CUSMA, CETA, and CUKTCA frameworks.
CBSA Verification Mandates & 2026 Priority Sectors
The Canada Border Services Agency periodically updates its trade compliance verification priorities to ensure the proper assessment and collection of duties, maintain fair market competition, and enforce compliance with Canadian trade legislation. The updated list outlines strategic audit targets across three primary trade programs: tariff classification, customs valuation, and origin determination. Importers handling targeted commodities can anticipate comprehensive verification letters and compliance audits in the upcoming fiscal quarters.
Historically, tariff classification audits generate the highest frequency of reassessments and retroactive duty adjustments. Under current CBSA enforcement directives, particular emphasis has been directed toward high-volume consumer goods, supply-managed agricultural categories, and precision electrical components. Importers are expected to possess documented technical specifications, lab analyses where required, and transparent classification rationale matching General Rules for the Interpretation (GRI) of the Harmonized System.
Proper customs compliance requires continuous internal review; assuming past declarations were accepted without scrutiny is a high-risk operational strategy in today's CARM-driven audit environment.
Sarah Jenkins, Senior Customs Compliance Instructor & Trade SpecialistSupply-Managed Imports & Sectoral Vulnerabilities
Special attention continues to fall on supply-managed agricultural imports and tariff rate quota (TRQ) classifications. Importers dealing in dairy blends, poultry preparations, and specialized grain products face exhaustive verification of ingredient percentages and production records to verify eligibility under specific tariff codes. Errors in these tariff lines carry substantial penalties and retroactive duty liabilities extending up to four years.
Furthermore, with the complete rollout of the CBSA Assessment and Revenue Management (CARM) system, the agency's data mining capabilities have expanded significantly. Audit selection algorithms now identify anomalies between customs documentation, commercial invoices, and electronic declarations with unprecedented speed.
Core Verification Streams & Legal Standards
The CBSA conducts audits under distinct statutory streams governed by the Customs Act. Importers must understand the technical criteria applied during administrative reviews:
Tariff Classification
Verifying accuracy of 10-digit Canadian tariff codes, chapter notes, and Explanatory Notes consistency.
Customs Valuation
Ensuring proper calculation of transaction value, assists, royalties, and subsequent proceeds under Section 48.
Origin Determination
Validating product-specific rules of origin, regional value content (RVC), and tariff shift criteria under trade pacts.
In addition to these core pillars, secondary reviews evaluate whether anti-dumping and countervailing duty assessments under the Special Import Measures Act (SIMA) apply to imported steel, fasteners, and solar components.
Risk Mitigation & Enterprise Preparedness
When an importer receives a CBSA Verification Letter, strict statutory timelines govern the submission of accounting documents, commercial contracts, bills of lading, and proof of origin. Importers typically have 30 to 90 days to provide full technical dossiers and substantiate declared customs values.
Failure to satisfy verification inquiries can trigger Redetermination of Tariff Classification or Valuation, resulting in detailed adjustment statements (DAS), retroactive duty assessments with interest, and Administrative Monetary Penalty System (AMPS) penalties. Companies must maintain thorough audit trails and internal control procedures for all imported merchandise.
Regular internal compliance reviews, staff training on customs valuation principles, and rigorous broker oversight remain the most effective strategies to withstand CBSA verification audits without disrupting cross-border trade operations.
Key Strategic Takeaways
Conduct periodic reviews of top Harmonized System codes and ensure full alignment with updated Explanatory Notes.
Maintain manufacturer certifications and bills of material supporting CUSMA and CETA claims for six full years.
Document all transfer pricing adjustments, freight costs, and assist payments factored into declared values.
Regularly review CARM Client Portal activity, delegation permissions, and daily notice notifications for audit flags.
Discussion & Professional Opinions
No comments yet. Be the first to leave a comment.
Contribute to Discussion